Financial Literacy
Why Do We Make Bad Financial Decisions Even When We Know Better?
Why do people make bad financial decisions even when they know better? Explore how emotions, comparison, habits, and digital convenience shape the way we spend.
- financial literacy
- financial decision-making
- emotional spending
- impulsive spending
- young adults
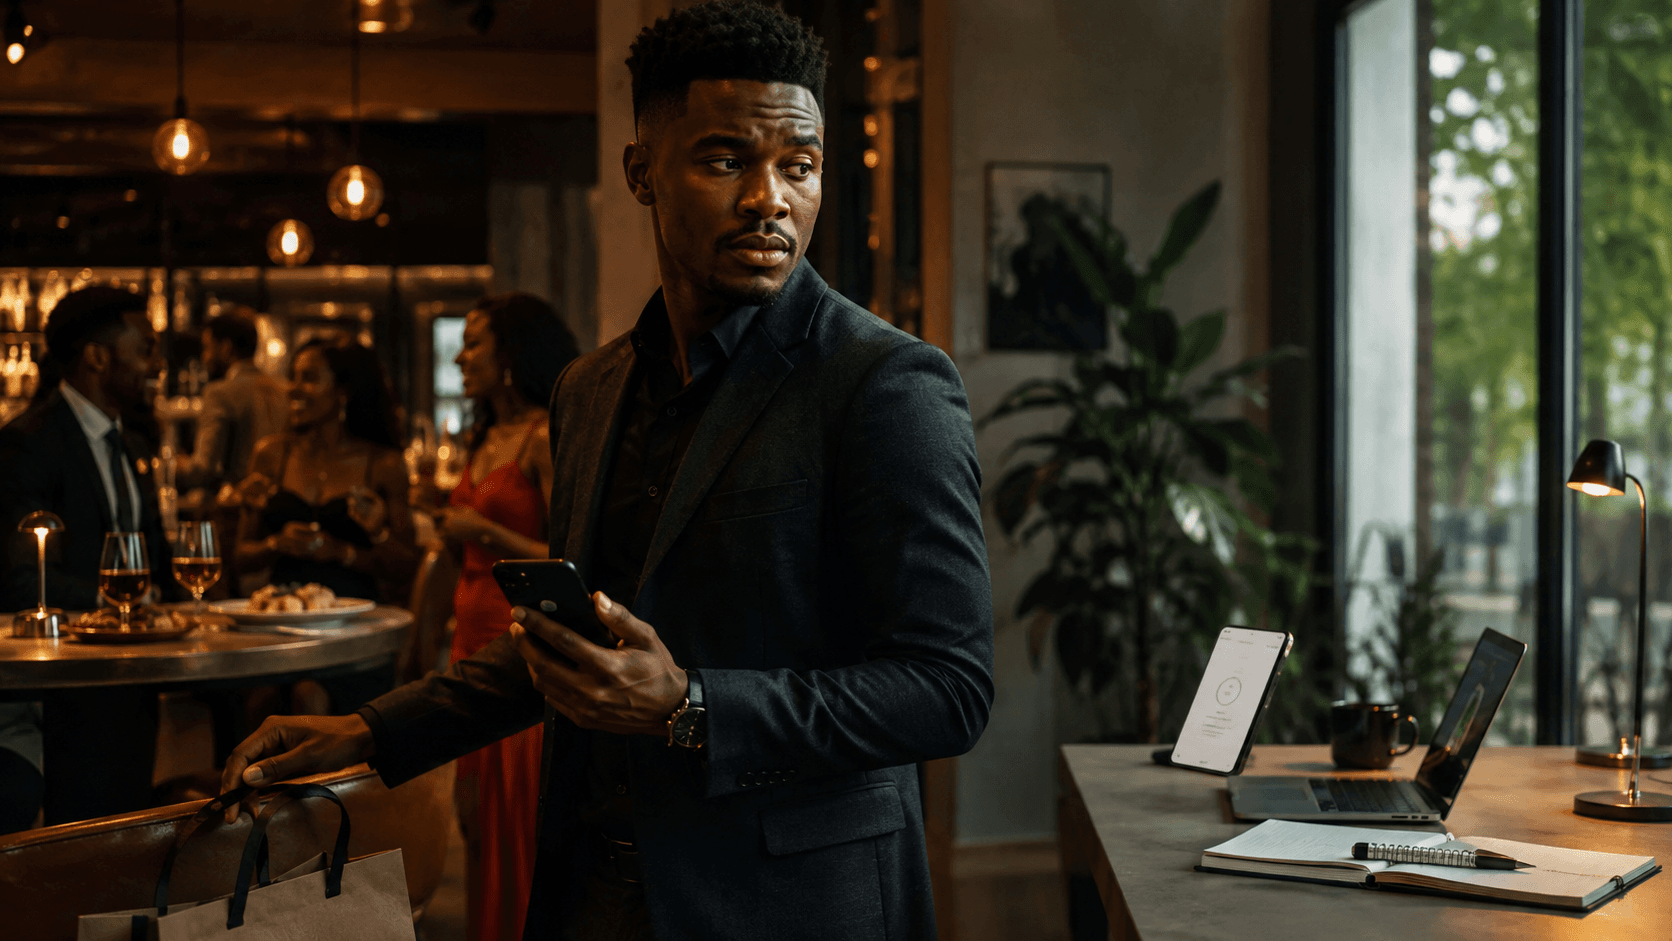
Published: August 2026
Image credit: AI-generated visual created with Google Gemini, 2026.
You can know exactly what you're supposed to do with your money and still do the opposite.
Save more. Spend less. Invest early. Avoid unnecessary debt.
We've heard the advice so many times that financial literacy can sometimes feel like common sense.
So why do smart people still make decisions they know aren't financially smart?
Maybe the problem isn't that we don't know enough about money.
Maybe we don't understand ourselves well enough.
Why Do We Spend Money We Know We Shouldn't?
Think about wanting something you don't really need.
Maybe it's a new phone, a pair of shoes, a night out or something you saw online. You know your money has other responsibilities, but suddenly the purchase feels justified.
"I deserve it."
"I'll replace the money later."
"It's only this once."
This is where financial decision-making becomes more complicated than simply knowing how to budget.
The OECD/INFE International Survey of Adult Financial Literacy looks at financial literacy through three connected areas: financial knowledge, behaviour and attitudes. That distinction matters because knowing the right financial decision and consistently making it are not necessarily the same thing.
What Actually Drives Our Financial Decisions?
Money decisions are rarely made in a vacuum.
Our emotions, habits, friends, family, environment and expectations can all influence what we do with our money.
The OECD's PISA 2022 research on students' spending and saving behaviours found that, on average across OECD countries and economies, 60% of students reported buying something because their friends had it. Nearly half also reported that they sometimes spend more than they would like when they are with friends.
That is an important distinction.
Sometimes the question isn't: "Can I afford this?"
It's: "Why do I want this so badly?"
That second question can reveal far more about our financial habits.
Who Are We Trying to Impress With Our Money?
There is another uncomfortable part of modern money management: comparison.
Someone gets a new car. Someone moves into a nicer apartment. Another person posts a holiday, a new business or a seemingly effortless lifestyle.
We see the result, but rarely the financial story behind it.
And comparison can quietly turn someone else's lifestyle into our financial target.
The danger is that appearances don't tell us whether something is affordable, financed, borrowed or simply unsustainable.
Financial freedom becomes difficult to build when we're constantly spending to keep up with a version of success that wasn't designed for us.
When Does Spending Become Emotional?
Not every unnecessary purchase is a financial crisis.
The problem begins when spending becomes a response to emotion rather than a conscious decision.
Stress can make us seek comfort. Celebration can make us spend freely. Social pressure can make saying no uncomfortable. Convenience can make us ignore the long-term cost of a small purchase.
Our increasingly digital lives can make this even easier. OECD research on digital financial literacy shows that digital financial literacy levels may not yet be sufficient to ensure safe and informed use of digital payments, highlighting the growing importance of understanding how digital finance shapes our behaviour.
When spending becomes one click away, the distance between wanting something and buying it becomes very small.
Where Does Better Financial Decision-Making Begin?
It begins with a pause.
Not every financial decision needs a spreadsheet. Sometimes it needs a better question.
Before making a purchase, ask yourself:
- Do I actually need this?
- Can I afford it without affecting something more important?
- Am I buying it because it adds value to my life or because I want to feel a certain way?
- Would I still want it tomorrow?
- What future goal am I giving up to have it today?
These questions don't make spending bad.
They make intentional spending possible.
How Can We Make Better Financial Decisions?
Financial literacy is often presented as learning the rules of money.
But perhaps the bigger challenge is learning the person making the decisions.
The Central Bank of Nigeria defines financial literacy as the possession of knowledge and skills to manage financial resources effectively and enhance economic well-being.
That definition matters.
Financial freedom isn't achieved by memorising financial advice. It's built by repeatedly turning knowledge into behaviour.
You don't need to become perfect with money.
You need to become more conscious of the decisions you make with it.
A Thought Worth Sitting With
Maybe financial literacy isn't just about learning how money works.
Maybe it's about learning why we behave the way we do when money is involved.
Because knowing what to do with your money is useful.
Knowing yourself well enough to actually do it is where the real work begins.
References
Share this article
Current series
Financial Literacy
A practical educational series on building healthy money habits before wealth arrives.
Part 3: Why Do We Make Bad Financial Decisions Even When We Know Better?
Related articles
The Life You Want Has a Financial Plan
Financial freedom is not only about earning more. It is about giving your money a clear direction toward the life you want.
Read article
Financial Freedom Begins Long Before Your First Million
Financial freedom starts with literacy, habits, and mindset long before a million-dollar bank account.
Read article
Financial Literacy Starts Before You Get Rich: Three Money Habits Every Young Adult Should Build
Financial literacy starts before wealth. Learn three practical money habits young adults can build now: track spending, save first, and avoid comparison.
Read article